Scandals & Feuds · 2010s
Neymar’s Transfer, the €88.4 Million Account, and Rosell’s Resignation
Barcelona completed Neymar’s move from Santos in June 2013, but the transfer’s financial structure soon drew a legal complaint, a tax payment, and scrutiny that reached the club presidency. Later Brazilian proceedings extended the financial dispute across borders without resolving the most serious allegations as criminal guilt.
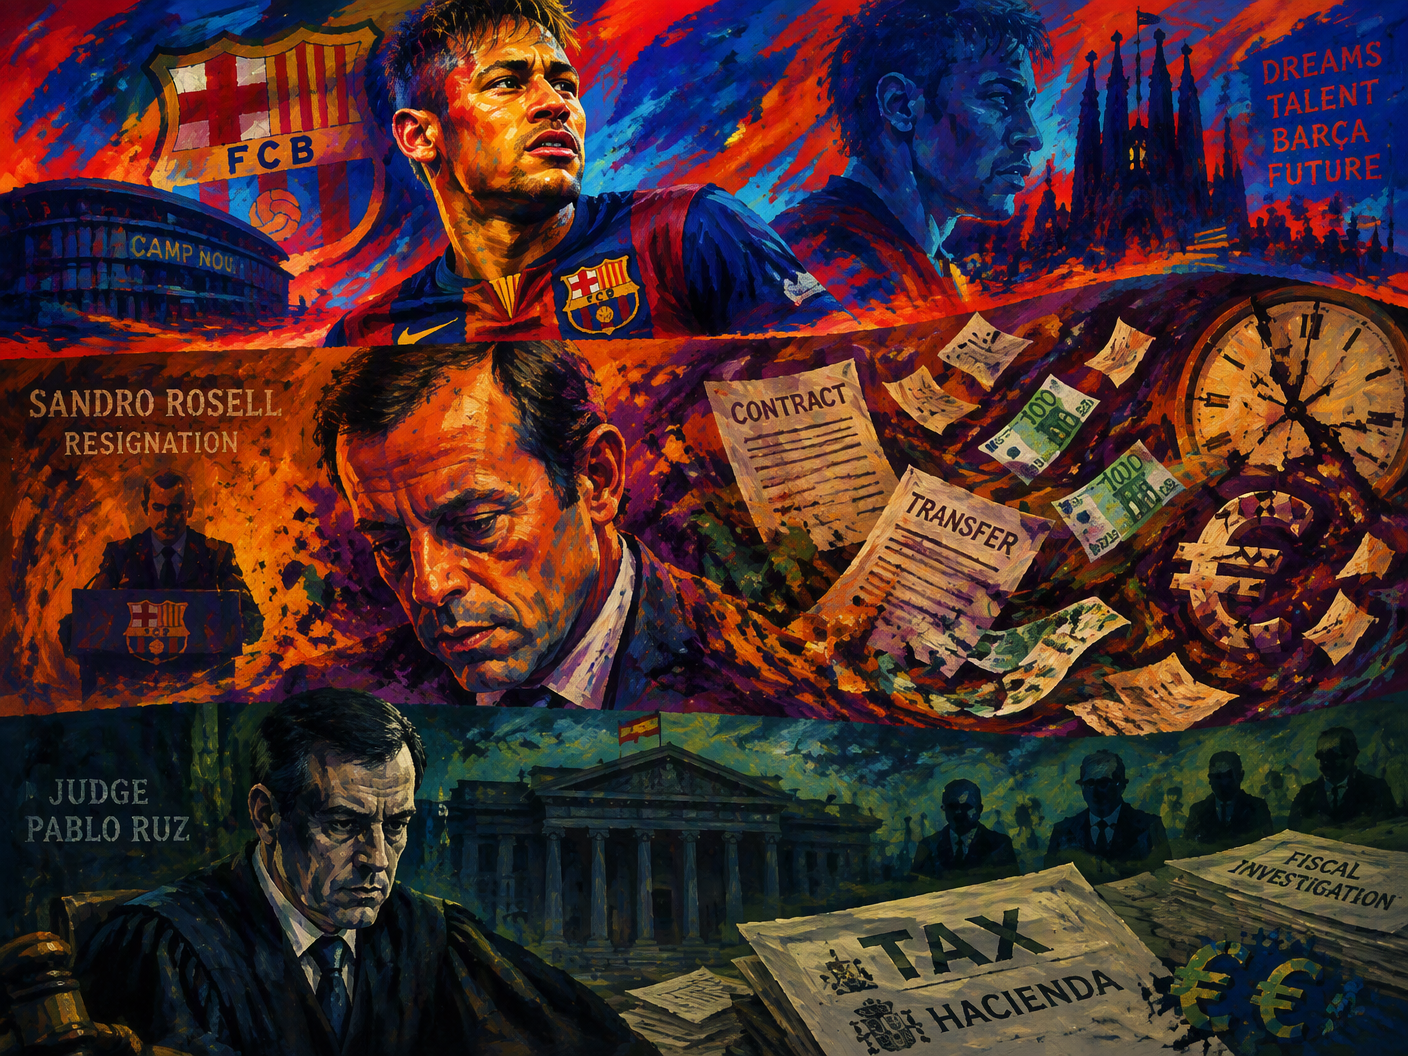
On January 23, 2014, Sandro Rosell resigned as president of FC Barcelona while the club’s acquisition of Neymar was under legal scrutiny. The decision changed the public meaning of a transfer that had begun less than eight months earlier as a carefully staged arrival. Neymar had come from Santos, passed his medical examination, signed a five-year contract, and been presented to Barcelona supporters. By the time Rosell left, the question was no longer simply what Barcelona had paid for a celebrated footballer. It was how the transaction had been assembled, disclosed, and taxed.
Barcelona completed the transfer on June 3, 2013. The announced figure was €57.1 million, and the agreement secured Neymar’s move from Brazil to Spain at the beginning of a five-year commitment. The club’s public presentation gave the deal a clean outline: a young star, a medical examination, a contract, and a new shirt. That outline would later prove incomplete as a financial description. Payments connected to the transfer and to Neymar’s commercial rights became part of the dispute, shifting attention from the football field to the contracts surrounding it.
For several months, the transfer occupied the ordinary place assigned to a major signing. Barcelona had obtained one of the most prominent players in South American football, and Neymar had entered one of Europe’s most powerful clubs. The public fee remained the reference point. Behind it stood a more complicated arrangement whose total value was not yet fully visible to members, tax officials, or the wider public. The distinction between a headline price and the full expenditure would become the central accounting question once the club’s own officials were required to explain the transaction.
In December 2013, Jordi Cases, a member of Barcelona, filed a legal complaint seeking clarity over alleged irregularities in the Neymar transfer. Cases was not acting as a prosecutor or club executive. He used his position as a member to force the transaction into a judicial setting, where contracts, payments, and corporate decisions could be examined through formal procedure. The complaint placed Rosell and the club’s handling of the signing under a different kind of pressure. A transfer celebrated as sporting progress had become a question for judges.
Judge Pablo Ruz accepted the case, and the complaint acquired a life beyond the complainant’s continuing involvement. That mattered in January, when Cases later withdrew it. Withdrawal did not close the inquiry because the judge had already admitted the matter for examination. The sequence revealed the difference between a private member’s initiative and a judicial proceeding once the court had taken jurisdiction. Barcelona could no longer treat the dispute as an internal disagreement over a club decision or as a passing argument about transfer accounting.
On January 24, the day after Rosell’s resignation, Barcelona’s financial director, Raul Sanllehí, disclosed that the club’s total expenditure on Neymar’s transfer had reached €88.4 million. The figure exceeded the €57.1 million announced at the time of the signing. The difference did not by itself determine whether anyone had committed a crime, but it transformed the public arithmetic of the deal. What supporters had been given as a single transfer fee now appeared as a larger financial undertaking involving additional commitments and related arrangements.
Rosell’s departure came as the club attempted to preserve institutional continuity. Barcelona remained in competition, Neymar remained under contract, and the board still had to operate while the legal process continued. Yet the presidency had become inseparable from the disputed transaction. His resignation placed the transfer at the center of the club’s governance rather than leaving it as a matter for lawyers and accountants alone. The leadership change also fixed the chronology: the complaint preceded the disclosure, and the disclosure stood beside the resignation as the controversy entered its formal phase.
The financial consequences followed quickly. In February 2014, Barcelona paid €13.5 million in back taxes related to the transfer. The payment gave the controversy a fiscal consequence beyond the competing explanations of the contract’s value. It also showed how the arrangement was being examined by more than one institution: the Spanish court considered the legal complaint, while tax authorities addressed the treatment of money connected to the deal. The same transfer now existed simultaneously as a sporting acquisition, a corporate transaction, and a tax matter.
The Spanish inquiry continued after Cases withdrew his complaint because Ruz had already accepted the case. That procedural fact kept the questions alive independently of the member who had initiated them. The allegations surrounding the transfer were therefore carried forward through judicial review rather than settled by withdrawal, resignation, or the club’s tax payment. Each action answered a different institutional demand: the complaint sought examination, the resignation addressed the presidency, and the payment addressed taxes. None erased the others.
The financial dispute later acquired a Brazilian chapter. In 2017, Neymar faced administrative tax proceedings involving the Receita Federal and the Brazilian tax appeals system, Carf. The case concerned an alleged omission of approximately R$65 million in income tied to the financial arrangements surrounding his image rights and transfer-related contracts. The tax authority’s assessment was stated as R$188.8 million and later exceeded R$200 million with interest. These figures carried the dispute far beyond Barcelona, into the country where Neymar’s professional career had begun.
By then, the original presentation at Barcelona had acquired a second life in legal and administrative files. The €57.1 million announcement remained part of the story, but so did the club’s later €88.4 million expenditure, the €13.5 million tax payment, Rosell’s resignation, and the continuing review after Cases withdrew his complaint. Neymar’s transfer was not undone. The contract remained a sporting fact even as its surrounding payments were examined by Spanish and Brazilian authorities through separate processes.
The enduring record is therefore a sequence of institutional responses rather than a single verdict: a completed transfer, a member’s complaint, a judge’s acceptance of the case, a presidential resignation, a tax payment, and later Brazilian assessments and appeals. The proceedings brought the economics of a celebrated signing into public view. They did not, within the documented events, convert every allegation into a criminal finding against Neymar or Rosell. What remained was a transfer whose public price could no longer contain its full legal and fiscal history.
Investigative Dossier & Evidence
Read the companion investigation notes, verified source claims, and primary documents.
Read the Companion Notes & Evidence Record →